Congress changes the tax rates
Public Law 119-21 · 139 Stat. 247
Open this page in the original document
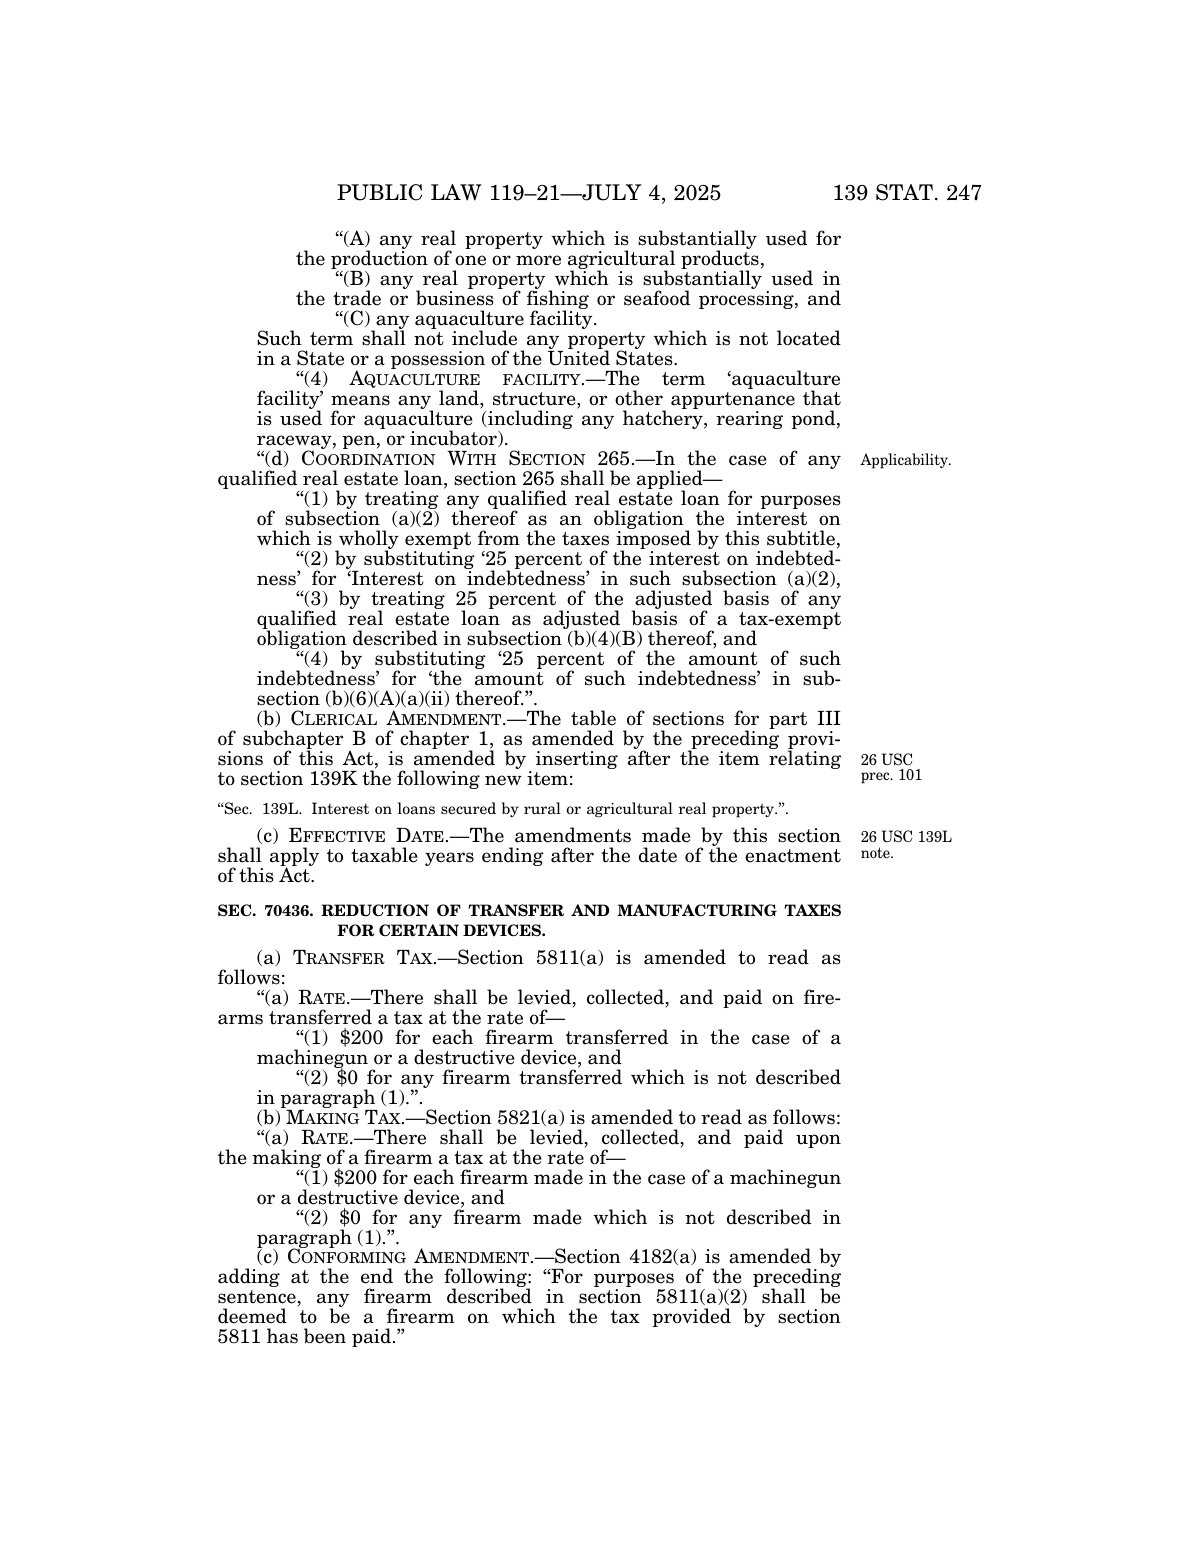
SEC. 70436. REDUCTION OF TRANSFER AND MANUFACTURING TAXES FOR CERTAIN DEVICES. (a) TRANSFER TAX.—Section 5811(a) is amended to read as follows: ‘(a) RATE.—There shall be levied, collected, and paid on firearms transferred a tax at the rate of— (1) $200 for each firearm transferred in the case of a machinegun or a destructive device, and (2) $0 for any firearm transferred which is not described in paragraph (1).’
Selected passage transcribed from the page. The full document includes surrounding provisions.
What to notice
The categories are defined elsewhere
The amendment keeps a $200 rate for machine guns and destructive devices. The $0 category includes silencers, short-barreled rifles, short-barreled shotguns, and ‘any other weapons’ covered by the NFA.
Making and transfer both change
Subsection (b) makes the same rate change for making a firearm. This section changes taxes; it does not itself strike the NFA’s registration provisions.
Enactment and operation are different dates
The effective-date clause is on the next printed page, 248. It applies the amendments to calendar quarters beginning more than 90 days after enactment, producing a January 1, 2026 start. The later litigation and enforcement policy are separate events.
U.S. government statutory text and official PDF; public domain in the United States. Full page reproduced without alteration apart from rasterization, resizing, and JPEG encoding.
Read this period’s history ↗