The original $200 transfer tax
National Firearms Act · 48 Stat. 1237
Open this page in the original document
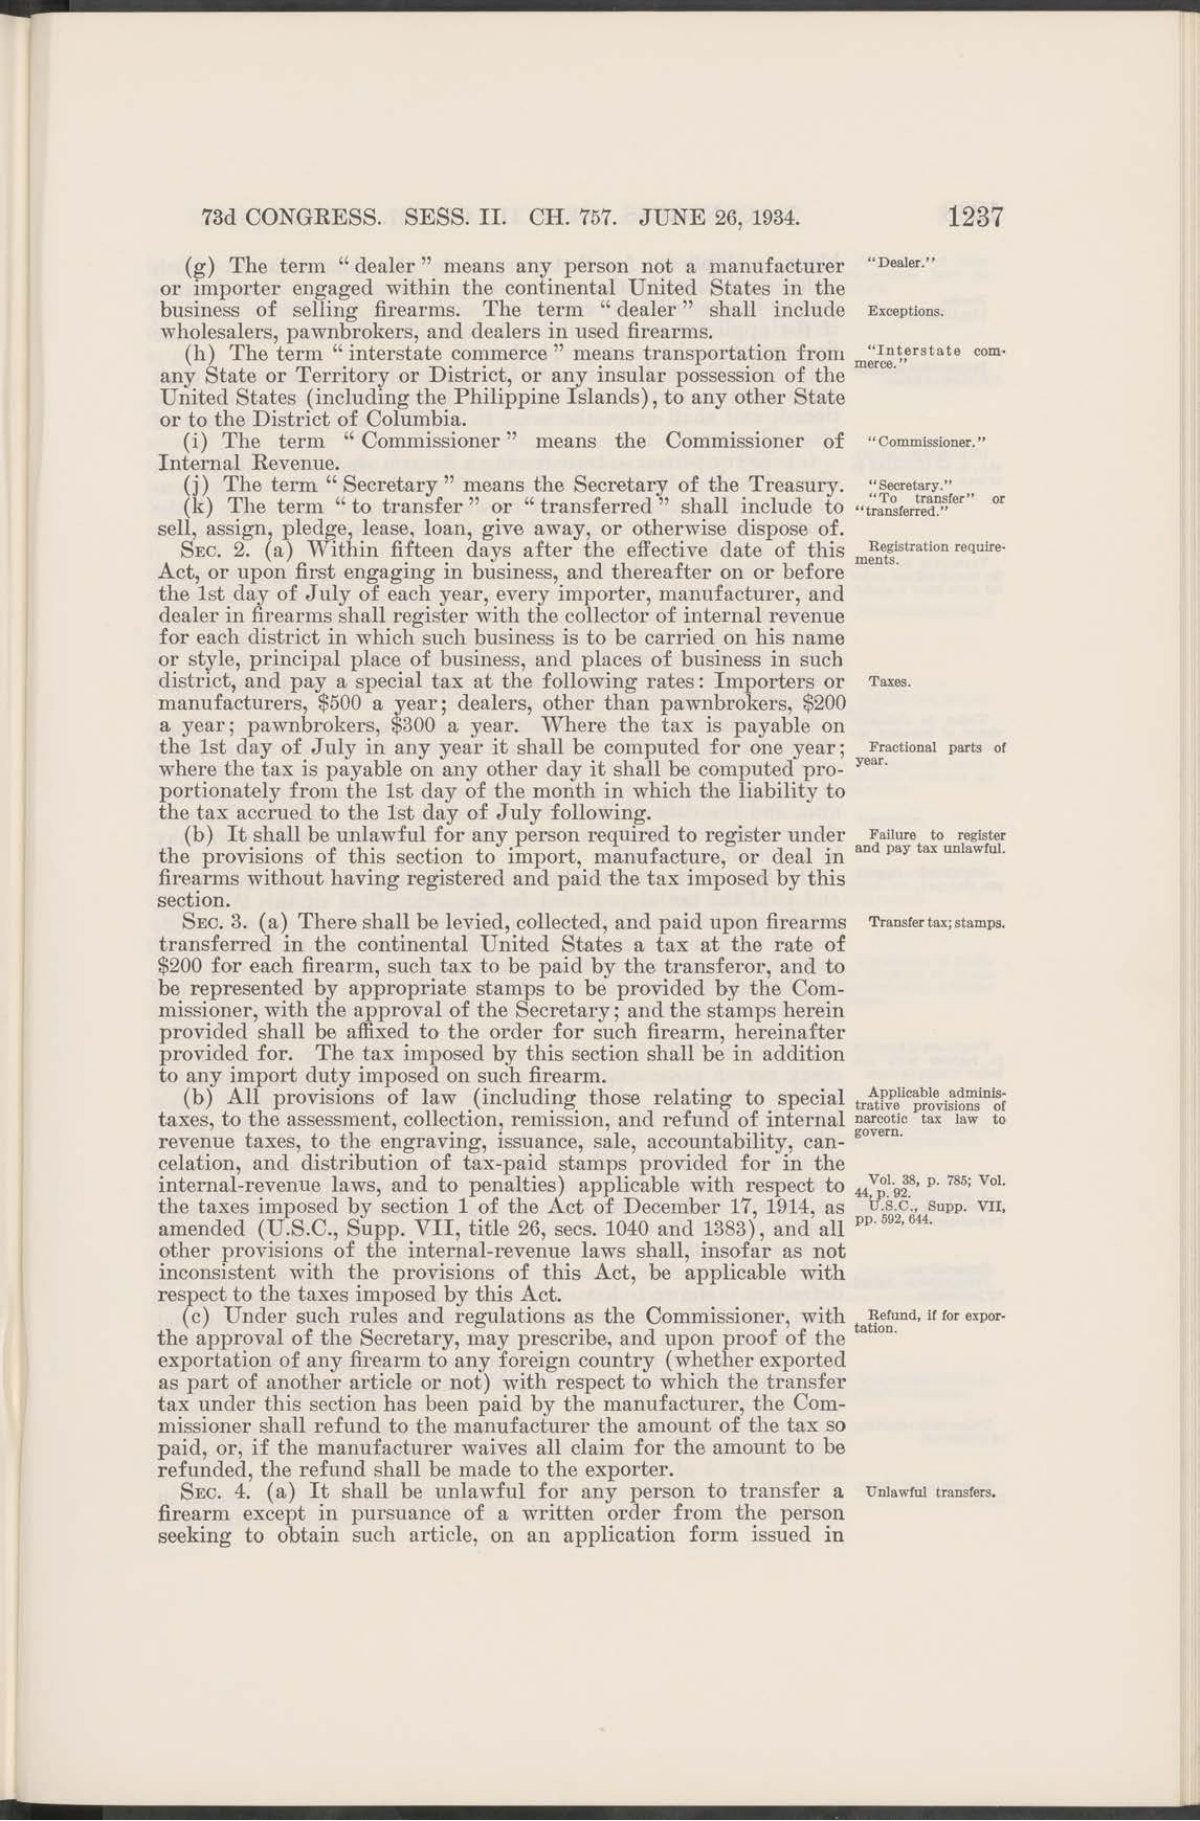
Sec. 3. (a) There shall be levied, collected, and paid upon firearms transferred in the continental United States a tax at the rate of $200 for each firearm, such tax to be paid by the transferor, and to be represented by appropriate stamps to be provided by the Commissioner, with the approval of the Secretary; and the stamps herein provided shall be affixed to the order for such firearm, hereinafter provided for. The tax imposed by this section shall be in addition to any import duty imposed on such firearm.
Selected passage transcribed from the page. The full document includes surrounding provisions.
What to notice
Two kinds of tax
Section 2, above the transfer provision, sets separate annual taxes: $500 for importers or manufacturers, $200 for dealers other than pawnbrokers, and $300 for pawnbrokers. These are the original 1934 rates.
More than a sale
The definition near the top includes assigning, pledging, leasing, lending, and giving away a firearm. Congress used ‘transfer’ to reach more than a cash purchase.
The stamp was evidence of payment
Section 3 directs that stamps be attached to the written order. The familiar tax stamp grew out of this revenue-law procedure.
U.S. government statutory text and official scan; public domain in the United States. Full page reproduced without alteration apart from resizing and JPEG encoding.
Read this period’s history ↗